Why early investigation matters
“In this edition, we look at why early and comprehensive investigation remains one of the most effective ways to control liability claims expenditure, protect evidential opportunities and support well-reasoned decisions from the outset.”
For Insurers and claims teams, the pressures are familiar. Claims need to be investigated properly, reserves need to reflect the evidence, costs need to be controlled, and decisions need to be supported by facts.
The earlier the right questions are asked, the clearer the picture becomes.
At MI Adjusting, our starting point is always the same: establish what actually happened before reaching a conclusion. Consider all evidence.
That means securing evidence while it is available, speaking to the people who were involved, identifying inconsistencies and areas of dispute, and providing clear, balanced advice at an early stage.
Good adjusting isn’t simply about producing a report or reaching a conclusion. It is about giving our Clients the information and insight they need to make confident decisions.
Helping reduce claims costs through expert investigation, technical analysis and efficient claims resolution.
The Momentum Continues – see how we are growing
MI Adjusting continues to achieve strong organic growth, driven by our commitment to exceed expectations and the deep trust of Clients. By consistently expanding our capabilities and strengthening relationships, without relying on acquisitions, we have naturally increased our market profile.
We’re delighted to share the news that MI Adjusting has been appointed to another leading Insurer’s liability adjusting panel.
Being selected to work with another Insurer is a great achievement for our team and reflects the confidence placed in us to provide technically strong, responsive liability adjusting services.
For us, it’s about more than just being simply appointed to a panel. It’s about the relationships we build, the quality of our work and the trust our clients place in us to handle claims with care and professionalism.
We’d like to thank everyone involved in securing this opportunity and all our existing Clients for their continued support and confidence in MI Adjusting.
THE CLAIMS INSIGHT
The following factors are common pressure points we see in liability claims. Each one can increase uncertainty, delay decision-making or add unnecessary cost if it is not addressed early enough.
Liability claims typically do not become complicated overnight. Instead, the challenges tend to accumulate gradually. This can happen for several reasons: evidence may not be collected promptly, a witness may become increasingly difficult to find, the initial account of events might be accepted without adequate scrutiny, or a claim may progress without a proper reassessment of the reserve.
Claims Trends and Observations
1. Delayed investigation
Time can negatively impact an investigation.
Witness recollections can change, CCTV footage can be overwritten, documents can disappear, and physical evidence may no longer be available.
The earlier an investigation begins, the greater the opportunity to establish an accurate picture of what happened.
Early investigation does not guarantee answers – but it greatly increases the chance of securing the evidence needed to understand the claim.
2. The initial version of events
The initial version of events is important, but it may not provide the full picture. A thorough liability investigation should consider a range of evidence, including witness statements, photographs, documentation, procedures, site conditions and the context surrounding the incident.
In some cases, the evidence may support the original account, while in others, it may contradict it.
The Adjuster’s role is to identify those differences and establish what the evidence tells us.
3. Not securing the right evidence
A liability decision is only as strong as the evidence behind it.
Knowing what evidence is likely to matter — and securing it early — can make a significant difference as a claim develops.
This is particularly important where liability, causation or quantum is likely to be disputed.
4. Reserves that don’t reflect the developing evidence
A claim can look very different six months after notification.
New evidence may strengthen the defence position, increase the potential exposure or reveal issues that weren’t apparent at the outset.
Regular review is therefore essential.
A reserve should reflect the evidence available today — not simply the information received at notification.
5. Failing to recognise when a claim needs to be escalated
Not every claim requires the same level of investigation.
Some can be dealt with quickly and proportionately. Others require more detailed investigation, technical input or specialist expertise.
Recognising which is which is an important part of effective claims management.
The objective isn’t to over-investigate every claim.
It’s to apply the right level of expertise at the right time.
OUR APPROACH
Evidence first. Confident decisions.
Our approach is straightforward.
- Investigate early.
- Establish the facts.
- Challenge assumptions.
- Provide clear advice.
- Keep the claim moving.
Insurers need more than a report. They need an Adjuster who understands the complexities of liability claims, knows what evidence that matters, and can translate that into clear, practical advice.
Our experienced liability team handle a broad range of claims, including:
- Employers’ Liability
- Public Liability
- Motor & RTA Liability
- Product Liability
- High-Value & Complex Claims
- Environmental Liability
- Sports Liability
Our focus is always on providing a service that is proportionate, technically sound and commercially practical.
Ultimately, good adjusting should make life easier for the claims team.
Clearer evidence. Better decisions. Claims that keep moving.
Case Analysis – When the Evidence Tells a Different Story
We were recently involved in a high-profile claim where, although liability was ultimately established, concerns arose at an early stage about the extent and severity of the claimant’s injuries and the length of time he remained off work. Given the potential value and associated heads of claim, we felt it was important to look more closely at the evidence.
Medical evidence was received, along with a Part 36 offer a little shy of £1 million. Fortunately, we had already taken the decision to place the claimant under surveillance on four separate occasions.
What emerged was significant. The primary injury identified by the medical experts did not appear consistent with some of the activities captured on the surveillance footage. The claimant was seen riding a bicycle, playing football and even fly fishing in a fast-flowing river, at times in water almost up to waist height.
The evidence we obtained materially strengthened our position and changed the dynamics of the claim. The matter ultimately settled before litigation for just over £230,000 — significantly below the initial settlement expectations.
This case is a good example of why claims should not always be taken at face value. A proactive and proportionate approach, combined with early investigation and the right evidence, can make a real difference to the way a claim develops and, ultimately to the cost of the outcome.
MEET THE TEAM
The People Behind the Claims
At MI Adjusting, we believe that good Adjusting is about people. Our team brings experience, technical knowledge and a willingness to ask the right questions and challenge assumptions when needed.
As our team continues to grow, we want to introduce you to one of the dedicated professionals behind the scenes.
An interview with Valery Jechiu LLB – Liability Adjuster
Valery joined MI Adjusting as part of the continued development of our liability team. With a background in law and experience in liability adjusting, she brings a useful combination of legal knowledge, investigative thinking and practical claims experience.
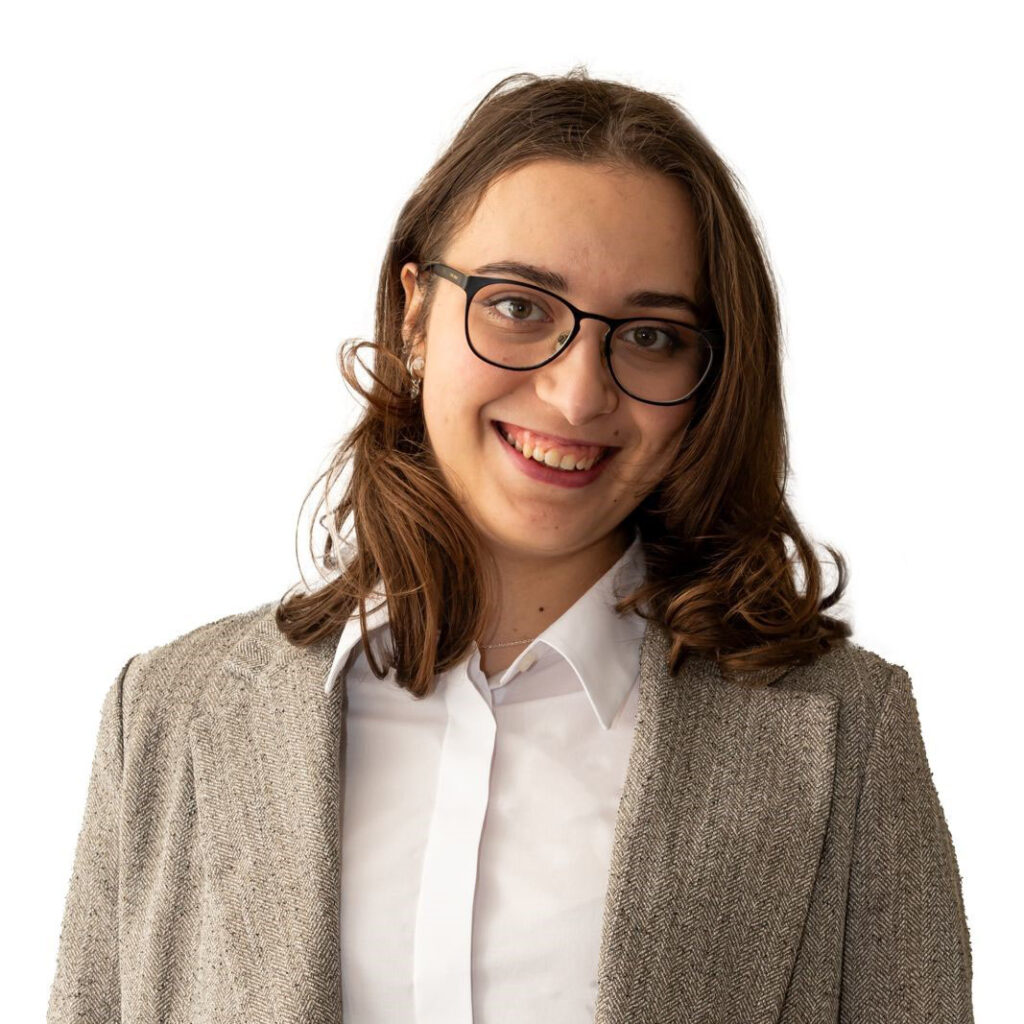
We asked Valery about her career, her approach to liability claims and what she enjoys about being an adjuster.
1. Tell us a little about your background and what brought you into insurance and adjusting?
Valery: I studied Law and graduated with a first-class LLB degree. During my studies, I became particularly interested in tort law and its relationship with insurance. That led me to look more closely at the role of a liability adjuster, as it combines investigation, evidence-gathering, legal knowledge and practical problem-solving. It was that combination that really appealed to me and led me into liability adjusting.
2. You have a Law degree. How does your legal background help when investigating liability claims?
Valery: My legal background is particularly useful when looking at the different elements of a liability claim, including duty of care, causation and the circumstances surrounding an incident. It also helps when considering policy coverage and identifying any indemnity issues, exclusions or relevant policy conditions.
That said, adjusting is not simply about applying the law. It is about establishing what actually happened, assessing the evidence and then applying the relevant legal and policy principles to the facts.
3. What do you enjoy most about being a liability adjuster?
Valery: I think being a liability adjuster is a little like being a detective. You’re reviewing documentation, gathering evidence, looking at CCTV, speaking to people and building a picture of what actually happened.
What I enjoy most is the variety. No two claims are the same, and there is always something new to consider. It keeps the job interesting and means you are constantly learning.
4. What makes a good liability investigation, in your opinion?
Valery: My mentor often describes investigating a claim is like solving a puzzle; the more pieces you have, the easier it is to make an accurate analysis of the relevant issues, and I think that is a good way of putting it. You need to understand the circumstances, look carefully at the evidence and importantly, consider the finer detail.
Timing is also important. There is a lot that can be lost as time passes, so getting involved early can make a real difference to the quality of the investigation and the evidence available.
An adjuster has to wear many different hats – investigator, analyst, communicator and sometimes a bit of a detective too.
5. What do you think Clients value most from their adjuster?
Valery: I think clients value reliability and communication. Meeting agreed timescales and SLAs is important, keeping the client informed about progress, and, importantly, exceeding their expectations.
I also think the real value of an adjuster is in the quality of the investigation and the advice that follows. Our role is not simply to collect information that a client could obtain themselves. We need to assess the evidence, consider the different possibilities and provide a clear, balanced view of the claim.
Ultimately, the client needs to understand the position and have confidence in the advice they are receiving.
6. What do you think people misunderstand about the role of an adjuster?
Valery: Sometimes there can be a perception, particularly among policyholders, that an adjuster is there to find fault with them. That is not the case.
Our role is to understand what happened, how the business operates and what the evidence tells us. We aim to help best protect their and the Insurer’s position.
By understanding those issues early, we can investigate them properly, give the insurer a balanced assessment and help determine the appropriate way forward.
7. What have you learned since joining MI?
Valery: Probably the level of attention given to the quality of every report. There is a real focus on looking at a claim from different perspectives, asking the right questions and making sure we have properly understood the evidence before reaching a conclusion.
It has made me think more about the responsibility that comes with the role. Behind every claim there are people and businesses, and our findings can have a real impact on them. That is something I think an adjuster should always keep in mind.
8. And finally, when you’re not investigating claims, what do you enjoy doing?
Valery: I enjoy getting lost in a good book, solving puzzles and exploring the countryside around North Yorkshire. I particularly enjoy going for a hike when I have the time.
There is something quite nice about getting out and switching off after a busy week. North Yorkshire has plenty of places to explore, so I am still finding new walks and views to enjoy.
THE INSURANCE NEWS
There are a number of developments worth keeping an eye on as we move towards the end of 2026, particularly around AI, claims outcomes and regulation.
AI: From Potential to Practical Use
AI is moving quickly from something Insurers are testing to a technology that is starting to play a practical role in day-to-day operations.
The FCA’s major review of AI, published in July, highlighted the potential for the technology to transform financial services, while also pointing to risks around fraud, cyber security, consumer harm and accountability.
For claims teams, the potential is clear. AI can help with document review, claims triage and identifying patterns across large volumes of information.
But liability claims are rarely straightforward. Understanding what happened, weighing conflicting evidence and assessing the circumstances of an incident still require experience and judgement.
For claims, we see AI as a useful tool rather than a replacement for experience and judgement. It can help find and analyse information more quickly, but securing all the relevant evidence and understanding the circumstances of a liability claim still requires an experienced professional.
Claims Outcomes Under Greater Scrutiny
The FCA is also continuing to look at how Insurers demonstrate value and claims outcomes.
In September, it launched a consultation on changes to its general insurance value measures regime. The measures include claims acceptance rates, average claim payouts and claims complaints. The FCA says the existing reporting has improved transparency, although inconsistencies in the data can make comparisons more difficult.
For Insurers, this reinforces the importance of good-quality claims handling and clear, evidence-based decision-making.
For liability claims, this also highlights the importance of early and comprehensive investigation. Establishing the facts while evidence is available and identifying potential issues early can help Insurers make better-informed decisions.

Independent. Experienced. Responsive. A Partner You Can Rely On.
For more than 20 years, MI Adjusting has provided specialised liability adjusting services to Insurers and self-insured organisations throughout the UK.
Our Clients rely on us to conduct thorough investigations, deliver clear, straightforward advice, and navigate the complexities of liability issues with a pragmatic, commercially focused approach. From first notification through to settlement, MI Adjusting provides independent expertise you can trust.
‘Adjusting as it should be’
Need a second opinion? – Speak to an Adjuster
If you have a liability claim that would benefit from an early view, a second opinion or further investigation, our Team is always happy to have an initial conversation.
Whether it’s a straightforward query or a complex claim requiring further investigation, we can help identify the next practical step.
Tina Whelan
Director of Operations & Business Services
M: 07966 559495
E: tina.whelan@miadjusting.com